Does Homeowners Insurance Cover AC Leak Damage in Texas?
Usually yes for the water damage, and usually no for the air conditioner itself. When people ask does homeowners insurance cover AC leak damage, the honest Texas answer is that a standard policy generally pays for sudden and accidental water damage, such as a ceiling soaked when a condensate line backs up, but it generally does not pay to repair the unit that leaked, and it often denies leaks that built up slowly over weeks or months. The cause, the timing and your maintenance history decide which side of that line your claim lands on.
- Often covered: a single-event overflow or backup that soaks ceilings, walls, flooring, insulation and belongings.
- Usually not covered: repairing or replacing the AC unit, drain line or pan that failed from age or wear.
- Often denied: slow drips, repeated overflows and damage tied to missed maintenance.
- Time matters: report the loss quickly and stop the water, or you risk a denial.
Dealing with an AC leak now? Call (945) 297-3238
This guide explains how Texas insurers treat AC leaks, which scenarios tend to be paid, why claims get denied, how to document the loss, and what to do in the first 24 hours. If the water is already inside your home, our team provides AC leak water damage cleanup in Frisco and can document the damage for your adjuster.
What Homeowners Insurance Usually Covers and Excludes After an AC Leak
Policies differ, so treat this table as a map of how claims are commonly handled, not a promise of coverage. Your declarations page, policy form and endorsements always control.
| Situation | How it is commonly treated | Why |
|---|---|---|
| Condensate line backs up once and soaks the ceiling and drywall | Resulting water damage is often covered | Sudden, accidental discharge from within the cooling system |
| Drain pan cracks or overflows in one event | Resulting damage often covered; the pan itself is not | The failed part is a wear item, the water damage is the covered loss |
| Loose or disconnected line drips for weeks | Often denied | Continuous or repeated seepage exclusion |
| Repair or replacement of the AC unit, coil or pump | Usually not covered | Wear and tear, deterioration, mechanical breakdown |
| Frozen coil melts and overflows the pan | Depends on the cause | Covered if sudden; questioned if a neglected filter or poor maintenance caused it |
| Mold that follows a covered AC leak | Limited | Mold on covered damaged property can be covered; cleanup and testing are often not included |
| Lightning, fire or storm damage to the unit | Often covered | A covered peril, which is different from a leak |
| Flooding from outside the home | Not covered | Standard policies exclude flood; a separate policy is needed |
The flood row matters in North Texas. If water entered from outside, read water damage versus flood damage and see whether you need flood insurance in Frisco.
Sudden vs. Gradual: The Line Insurers Use on AC Leaks
Almost every AC leak claim turns on one question: was the water released suddenly, or did it seep over time? The Texas Department of Insurance explains that most home policies cover sudden and accidental water damage, such as a burst pipe, a toilet overflow or a broken washer hose, but most do not cover damage from gradual leaks or seepage, or the mold that results.
Texas policy forms word this exclusion differently. The TDI’s summary of Texas homeowners policies shows that some forms exclude constant or repeated leakage from a plumbing, heating or air conditioning system over a period of 14 or more days, while others use the phrase “weeks, months or years.” Both versions give an adjuster room to deny a slow AC drip.
A simple way to see the difference:
- Sudden: the float switch fails during a heat wave, the pan overflows overnight, and you find a soaked ceiling the next morning.
- Gradual: a loose fitting drips onto the same drywall for two months, leaving a brown ring, soft insulation and a musty smell.
Adjusters look for evidence of duration: rusted pans, layered stains, rotted framing and mold. A written note from your HVAC technician describing what failed, and when, can be the strongest document in your file.
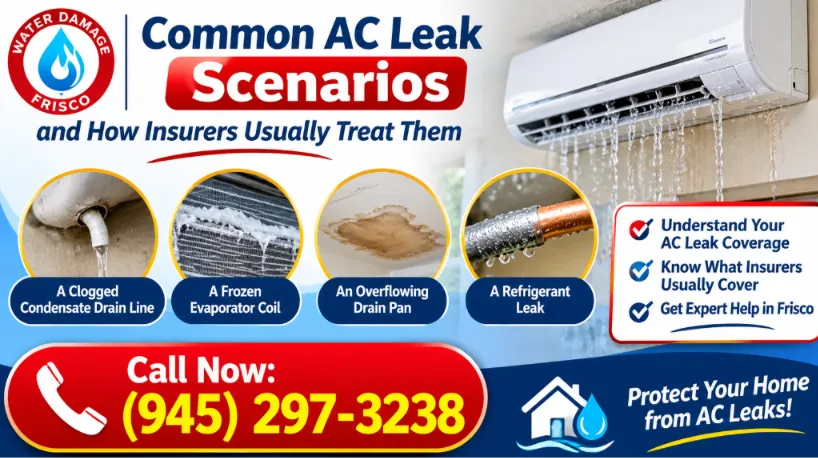
Common AC Leak Scenarios and How Insurers Usually Treat Them
A clogged condensate drain line
Algae and sludge build up in the line, the water has nowhere to go and it backs up into the pan or the ceiling. Unclogging the line is maintenance. The water damage may be covered if the backup was a single event. If it happened repeatedly, the insurer may call it a maintenance issue. Our guide to a clogged AC drain line shows the warning signs to catch early.
An overflowing drain pan with a failed float switch
The float switch should shut the system down when the pan fills. When it fails, the pan overflows. See how an overflowing AC drain pan and float switch work together. A one-time failure is easier to present as accidental than a pan that has been overflowing for a season.
A frozen evaporator coil that thaws
Restricted airflow or low refrigerant ices the coil, and the melt overwhelms the pan. Insurers will ask why it froze, so read about an AC freezing up and then leaking and keep your filter-change records.
An attic air handler leaking into the ceiling
This is the classic North Texas claim. The leak is hidden above the ceiling until a stain appears, so duration is the issue the adjuster will question. Moisture mapping and photos matter here, and our steps for an AC leaking into the ceiling explain what to do before the drywall comes down. For the repair side, see ceiling leak repair in Frisco.
A refrigerant leak
A refrigerant leak is not a water loss, and insurers typically treat it as mechanical failure or corrosion, so it is generally not covered unless a covered event physically damaged the system.
For the full picture of causes in local homes, read why an AC leaks water in Frisco homes.
Is the AC Unit Itself Covered When It Leaks?
In most cases, no. Homeowners insurance is built to pay for unexpected damage to your home and belongings, not to replace equipment that wore out. A compressor that fails from age, a corroded coil or a cracked pan will usually be treated as wear and tear. Some policies pay reasonable costs to tear out and replace parts of the home to reach a covered leak, so ask your agent whether yours does.
Insurance can pay for the equipment when a covered event caused the damage, for example lightning, fire or a falling tree limb. For age-related breakdowns, a home warranty may be the better fit. Whatever pays for the unit, the water that escaped is a separate loss, and that is the part most worth documenting. If the water also reached the system, our overview of HVAC problems after water damage covers what to inspect.
What About Mold From an AC Leak?
Mold is where AC leak claims get complicated, because moisture in an attic or wall cavity can grow it within days. The TDI says mold that develops on property damaged by a covered event is covered, while mold from gradual leaks is not, and that most policies do not include mold cleanup and testing after the damaged item is removed unless you add that coverage. Ask your agent whether a mold endorsement is part of your policy.
If your claim involves mold, the TDI advises using a state-licensed mold professional and getting a certificate showing the mold was removed and the cause was fixed. Learn more about mold growing after an AC leak, what to do about a denied Texas mold insurance claim, and how we handle mold remediation in Frisco. To keep it from starting, see mold prevention in attics, garages and closets.
What to Do in the First 24 Hours After an AC Leak
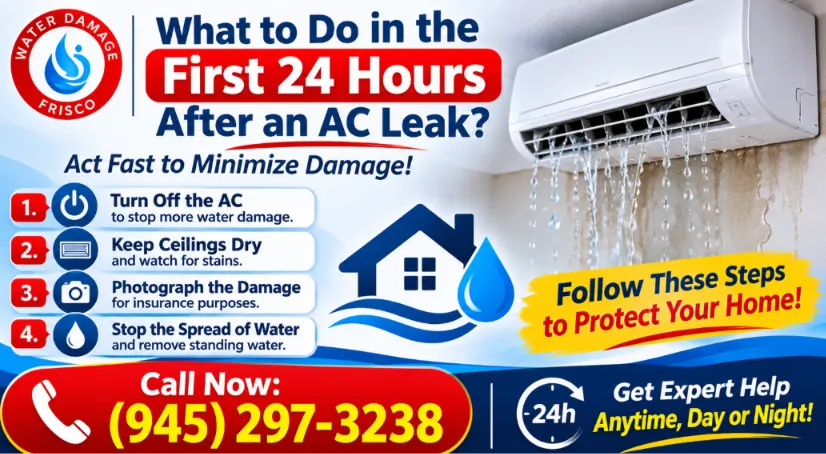
What you do in the first day affects both the damage and the claim. Follow these steps in order:
- Turn off the AC. Switch the system off at the thermostat. If water is near the air handler, a light fixture or an outlet, also switch off the breaker so the unit stops producing condensate and the electrical risk is removed.
- Keep clear of sagging ceilings. A bulging or stained ceiling can hold gallons of water and may drop without warning. Stay out from underneath it and keep children and pets away.
- Photograph and film everything first. Record the unit, the drain line, the drain pan, the wet ceiling, floors and belongings with date-stamped photos and video before anything is moved or cleaned.
- Stop the spread of water. Remove standing water, move furniture and valuables to a dry room and start airflow. Insurers expect reasonable steps to limit further damage, and the Texas Department of Insurance warns that a claim can be denied if you do not protect your property.
- Report the loss to your insurer. Call the claims line as soon as possible, state that the damage came from sudden water discharge from the air conditioning system, and write down the claim number, date and the name of the person you spoke with.
- Keep damaged materials and receipts. Save wet insulation, drywall pieces and padding until the adjuster has seen them, keep every receipt for emergency work, and hold off on permanent repairs until the insurer has inspected the damage.
- Call a restoration team to dry and document. Professional extraction, drying equipment and moisture readings stop secondary damage and give your adjuster the measurements they need.
Water from a condensate line can carry bacteria and mold spores, especially after it has sat in insulation, so do not assume it is harmless. Our explanation of water damage categories shows how contamination level changes the cleanup. For a longer checklist, read the first 24 hours after water damage.
Wet ceiling or soaked floors from an AC leak?
Our Frisco crew extracts water, dries the structure and documents moisture readings for your adjuster.
Call (945) 297-3238 Get AC Leak Damage Help: (945) 297-3238How to File an AC Leak Insurance Claim in Texas
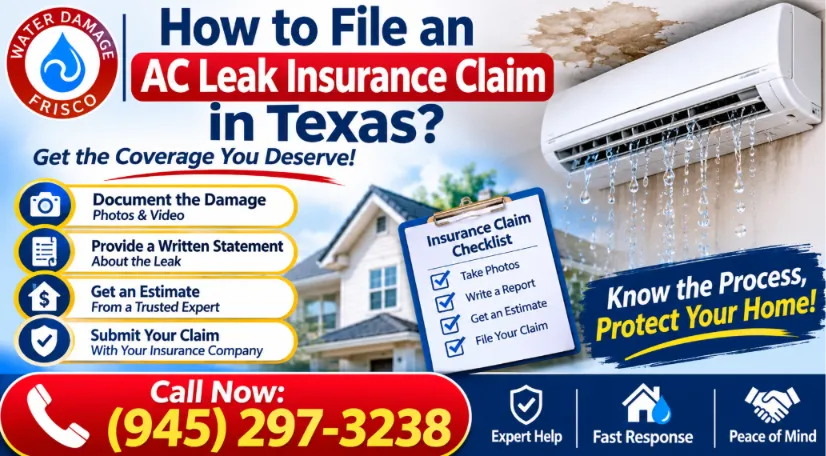
The TDI tells homeowners to report water damage as soon as possible, and says damage hidden from view usually must be reported within days after you first see it. It also advises you to document the damage with a list, photos or videos before repairs, make temporary repairs to limit further damage, keep receipts and avoid permanent repairs until the insurer has seen the damage. For the full process, see our Texas water damage insurance claim guide.
- Date-stamped photos and video of the unit, drain line, pan, float switch and every wet area
- A written statement from your HVAC technician naming the failed part and whether it failed suddenly
- Proof of maintenance, such as tune-up invoices and filter-change dates
- Moisture readings and a drying log from your restoration company
- An itemized estimate for the water damage, kept separate from the AC repair invoice
- A list of damaged belongings with age, purchase price and photos
- Your claim number, adjuster name and the date and time of each call
Ask your adjuster to list the AC repair and the water damage as separate items. That separation helps because the unit is typically a maintenance item and the resulting water damage is the part that may be covered. Our crew can provide the equipment logs and moisture readings for the water side; to see how long that work usually takes, read how long water damage restoration takes.
Why Insurers Deny AC Leak Claims and What You Can Do
These are the most common reasons a claim is denied or reduced:
- The leak looks gradual. Rust, layered stains, soft framing or visible mold suggest long-term seepage.
- Maintenance was neglected. A clogged drain line or filter can be described as a preventable maintenance failure.
- Late reporting. Waiting weeks after you first noticed the stain weakens the claim.
- No mitigation. The TDI notes your insurer may deny a claim if you do not protect your property after a leak.
- The request was for the unit. Claims to repair or replace a worn AC are usually declined as wear and tear.
- Mold with no covered cause. Mold alone, with no covered water event, is frequently excluded.
If you receive a denial, ask for the reason in writing, compare it with the exact policy language, and send any missing evidence, such as the technician’s report and maintenance records. You can ask for a re-inspection. The TDI also offers help with questions and issues with your insurance company or agent, and its general questions line is 800-252-3439.
Should You File? The Deductible Math
A claim only helps when the covered damage is larger than your deductible. As a hypothetical example, if your deductible is $2,500 and the ceiling, insulation and paint estimate is $1,800, filing will not pay you anything. If water reached the walls, flooring and wet carpet padding and the estimate reaches $9,000, a claim is worth discussing with your insurer.
Get the estimate first. Use our water damage cost calculator for a ballpark, read about water damage restoration cost in Frisco, and ask your agent how a claim could affect your renewal before you decide.
Homeowners Insurance vs. Home Warranty vs. Flood Insurance for AC Problems
| Coverage | What it is built for | AC leak fit |
|---|---|---|
| Homeowners insurance | Sudden, accidental damage to the home and belongings | Best for resulting water damage from a single-event leak |
| Home warranty | Repair or replacement of covered systems that wear out | May cover the failed AC part; often excludes damage to ceilings and floors |
| Flood insurance | Surface water entering the home from outside | Not relevant to a leak from inside your AC system |
Many Frisco homeowners need two of the three working together: insurance for the water damage and a warranty or a repair budget for the equipment.
How to Prevent an AC Leak Claim Before It Happens
Preventing the leak is cheaper than arguing about coverage. North Texas summers keep air conditioners running for months, so condensate lines and pans work hard.
- Have a licensed technician service the system before summer and keep the invoice.
- Clear the condensate line on a schedule and confirm the secondary pan drains properly.
- Install a float switch that shuts the system off when the pan fills.
- Replace filters on time so the coil does not freeze.
- Put a water sensor under the air handler. Read about smart leak detectors and shut-off valves.
- Check the ceiling below your attic unit for stains every few months.
Other home leaks follow similar rules. If you want to compare, see how insurers handle a water heater leak, a washing machine leak, a sink leak, a toilet overflow and burst pipes.
Frisco Permits, Contractors and Local Resources
Replacing an air handler or doing larger repair work can involve permits, so check before work begins. The City of Frisco Building Inspections Division says to contact a Building Inspections representative before starting work if you are unsure whether you need a permit, and its customer service line for permits and registration is 972-292-5301. The city also publishes contractor registration information you can review before hiring.
We serve the whole city, from our Frisco service area to the communities in our Frisco neighborhoods water damage guide, and our emergency water damage restoration in Frisco team is available when water is still spreading. For broader work after an AC leak, see water damage restoration in Frisco.
Frequently Asked Questions About AC Leaks and Homeowners Insurance
Does homeowners insurance cover AC leak water damage to my ceiling and walls?
Often yes, when the leak was sudden and accidental, such as a condensate line that backed up or a drain pan that overflowed in a single event. Texas Department of Insurance guidance says most policies cover sudden and accidental water damage but usually not gradual leaks or seepage. Your policy wording and the cause of the leak decide the outcome.
Will insurance pay to repair or replace the leaking AC unit?
Usually not. A unit that fails from age, corrosion or missed maintenance is generally treated as wear and tear. Insurance may pay for the equipment when a covered event such as lightning or fire damaged it. A home warranty may cover age-related breakdowns, depending on its terms.
Is a clogged condensate drain line covered by homeowners insurance?
Clearing the clog is a maintenance cost and is not covered. The water damage it causes may be covered if it happened suddenly, but a line that dripped for weeks can be treated as gradual leakage and denied.
How soon must I report an AC leak to my insurance company?
As soon as possible. The Texas Department of Insurance says damage hidden from view usually must be reported within days after you first see it. Read the notice requirements in your policy and call your insurer promptly.
Does homeowners insurance cover mold after an AC leak?
The Texas Department of Insurance says mold that develops on property damaged by a covered event is covered, while mold from gradual leaks is not. Most policies also do not include mold cleanup and testing once the damaged item is removed unless that coverage has been added.
Does a home warranty cover an AC leak?
It depends on the contract. Many home warranties cover repair of the failed HVAC part but exclude resulting damage to ceilings, floors and belongings, so confirm the wording before you rely on it.
Will filing an AC leak claim raise my premium?
Insurers may consider claim history when they price or renew a policy, and the rules vary by company. Ask your agent before filing, and compare your deductible with the repair estimate first.
I rent my home in Frisco. Who pays for AC leak damage?
The landlord’s policy generally protects the building, while your renters policy may cover your own belongings after a sudden leak. Report the leak to your landlord in writing right away and read our guide to Texas tenant water damage rights.
Need Help With AC Leak Water Damage in Frisco?
We are a restoration company, not an insurer or a public adjuster. What we do is stop the water, dry the structure and give you clear documentation so your claim rests on measurements rather than guesswork. If you are unsure where to start, contact our Frisco restoration team and we will talk through your situation.
Talk to a Frisco water damage specialist today
Fast response, moisture documentation and straight answers.
Call (945) 297-3238 Request Help Online: (945) 297-3238This article is general information, not legal or insurance advice. Coverage depends on your policy, its endorsements and the facts of the loss, so confirm details with your insurer or agent. Sources: Texas Department of Insurance, When are water damage and mold covered by insurance, Texas Department of Insurance, Texas homeowners policies and the City of Frisco Building Inspections Division.