Does Homeowners Insurance Cover Sink Leak Damage? The Short Answer for Texas
Short answer: yes, in most cases, if the leak was sudden and accidental. A standard Texas homeowners policy generally pays for the water damage a sudden sink or plumbing leak causes to your cabinets, floors, drywall and belongings, after your deductible. It generally does not pay to fix the leaking faucet, pipe or fitting itself, and it typically excludes damage from a leak that dripped for weeks or months.
So, does homeowners insurance cover sink leak damage in your home? The answer depends on three things: how fast the water escaped, what it damaged, and whether your policy has any limits or endorsements that change the standard rules. This guide walks through each one, shows what Texas insurers usually look for, and explains the first steps that protect your claim. For the full process from start to finish, read our Texas water damage insurance claim guide.
Sink leak just happened? Stop the water, then call us.
We can help you dry out the cabinet, floor and walls quickly so the damage does not spread while you talk to your insurer.
Sink Leak Insurance Coverage at a Glance
Use this table as a starting point. Your own policy wording always controls the final answer.
| Sink leak situation | Usually covered? | Why |
|---|---|---|
| Supply line bursts and floods the cabinet and floor | Usually yes | Sudden and accidental discharge of water |
| Slow drip from a loose trap or fitting for months | Usually no | Continuous or repeated seepage is commonly excluded |
| Replacing the leaking faucet, trap or supply line | Usually no | The failed part is a maintenance and wear item |
| Opening a cabinet back or drywall to reach the leak | Often yes | Tear-out access is often paid when the leak is covered |
| Mold after a sudden, covered leak | Often yes | May be limited by a mold cap in your policy |
| Mold from a long-ignored leak | Usually no | Follows the excluded slow leak |
| Sink overflow from an accident | Depends | Accidents are often covered; neglect can be disputed |
| Higher water bill from a hidden leak | Usually no | Not property damage, but Frisco offers a leak credit |
Sudden and Accidental vs. Gradual Leaks: How Insurers Decide
Almost every sink leak claim comes down to one question: did the water escape suddenly, or did it seep for a long time? The Texas Department of Insurance explains that home policies cover sudden, accidental water damage, such as a burst pipe, an overflowing toilet or a broken washer hose, while slow leaks and seepage are usually not covered. You can read the agency’s own wording in its guidance on water damage and insurance.
Some policies use the phrase “continuous or repeated seepage or leakage over a period of time.” Others name a specific number of days, commonly 14. Whether your policy follows a Texas HO-A or HO-B style form or an insurer’s own proprietary form, the logic is the same.
What adjusters look for
- Rot, rust and staining. Soft, dark or swollen cabinet floors suggest long exposure, not a recent event.
- Mineral crust and corrosion. Deposits around a fitting point to a slow weep.
- Mold growth. Established colonies usually take more than a few days to form.
- The failed part. A cracked or split supply line supports a sudden failure.
- Your timeline. When you first noticed water, when you stopped it and when you reported it.
Hidden leaks are the gray area. If the water was inside a wall or cabinet and you had no way to see it, say so plainly and show the evidence. Our guide to hidden water damage signs in Frisco homes explains what to look for, and our article on water leaking under the kitchen sink covers the most common causes.
What a Texas Homeowners Policy Usually Pays for After a Sink Leak
When the leak is a covered event, the policy generally responds to the damage the water caused:
- Cabinets, countertops and the sink base
- Flooring and subfloor, including hardwood, laminate and tile underlayment
- Drywall, insulation and baseboards near the leak
- Belongings stored under the sink or in nearby cabinets
- Tear-out and replacement of building parts needed to reach the plumbing, in many policies
- Reasonable emergency steps to limit further damage, such as water extraction and drying. See whether insurance covers water mitigation for details
If the kitchen becomes unusable, some policies also include loss-of-use coverage. That is rare for a small sink leak, but it is worth asking about when a larger area is affected. For how the drying work is done, see our water mitigation service overview.
What Homeowners Insurance Usually Does Not Pay For
- The failed part itself. The faucet, trap, supply line or angle stop is generally your maintenance responsibility.
- Long-term seepage. Damage from a leak that continued over weeks or months is commonly excluded.
- Wear, corrosion and neglect. Insurers separate sudden failures from deterioration you could have caught.
- Flood and surface water. Rising water from outside needs a separate flood policy. TDI notes that home policies do not cover floods.
- Sewer or drain backup. Water pushed back up through a sink drain from the main line is a different peril and often requires a water backup endorsement. That water is also more hazardous; see our explanation of water damage categories.
Plumbing Leaks Beyond the Sink: Supply Lines, Drains and the Slab
Many “sink leaks” are really plumbing leaks under or behind the sink. Dishwasher and disposal connections share the same cabinet, so a leak there is judged the same way. See our guides to a dishwasher leak under the sink cabinet and a leaking garbage disposal. If a pipe inside the wall is the source, our article on the signs of a burst pipe in a wall will help you recognize it.
Texas adds one more wrinkle: foundation damage. Many homes here sit on slabs over expansive clay, and a leak in a pipe under the slab can affect the foundation. Policies often treat foundation damage from plumbing leaks differently, sometimes excluding it or limiting it to a percentage of the dwelling limit unless an endorsement is purchased. Check your declarations page, then read about a slab leak in Frisco and the foundation risk from untreated water damage.
Other leak sources follow similar rules, and we cover them separately so you can get the specifics: does homeowners insurance cover burst pipes, does homeowners insurance cover a water heater leak and does homeowners insurance cover a toilet overflow.
Mold After a Sink Leak: Covered or Not?
Water trapped inside a cabinet is a perfect place for mold. TDI says mold that develops on property damaged by a covered sudden leak is covered as well, while mold from slow leaks is generally not. Some policies set a dollar limit on mold, so the payout may be smaller than the cleanup bill.
Dry the area fast. Mold can begin to grow within a couple of days in a damp, closed cabinet. Read our guides to mold under the kitchen sink and mold after water damage in Frisco, and see why some Texas mold insurance claims are denied. If mold has already spread, our mold remediation service in Frisco can assess it.
Should You File a Claim for a Sink Leak? Compare the Damage to Your Deductible
Not every sink leak is worth a claim. If your deductible is higher than the repair estimate, the insurer will pay nothing. For example, with a $2,500 deductible and $1,800 of cabinet and flooring repairs, the claim pays $0. Many Texas policies use a flat dollar deductible for water damage, but some use a percentage of the dwelling limit, so read your declarations page.
Also remember that claims can appear in loss-history reports that insurers review at renewal or when you shop for coverage. A practical approach:
- Get a written repair and drying estimate before you decide.
- Compare it with your deductible.
- Ask your agent how a claim may affect renewal.
- If the damage is large, hidden or still spreading, file the claim and let the adjuster evaluate it.
Our water damage cost calculator can give you a rough idea of the repair range before you call your insurer.
Not sure the damage is worth a claim?
Call us for a quick assessment of the water damage so you can decide with real numbers in hand.
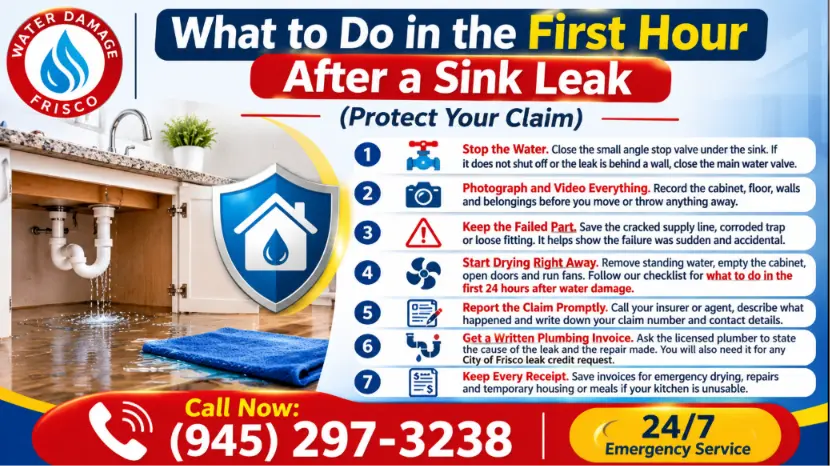
What to Do in the First Hour After a Sink Leak (Protect Your Claim)
What you do in the first hour affects both the damage and the claim. Follow these steps in order:
- Stop the water. Close the small angle stop valve under the sink. If it does not shut off or the leak is behind a wall, close the main water valve for the house. Our guide shows how to shut off the main water valve in Frisco, and the City of Frisco FAQ on the customer water shut-off explains where the city-side valve usually sits.
- Photograph and video everything. Record the cabinet, floor, walls and belongings before you move or throw anything away.
- Keep the failed part. Save the cracked supply line, corroded trap or loose fitting. It helps show the failure was sudden and accidental.
- Start drying right away. Remove standing water, empty the cabinet, open doors and run fans. Follow our checklist for what to do in the first 24 hours after water damage. Insurers can deny a claim if you do not protect the property from further damage.
- Report the claim promptly. Call your insurer or agent, describe what happened and write down your claim number and the adjuster’s contact details.
- Get a written plumbing invoice. Ask the licensed plumber to state the cause of the leak and the repair made. You will also need it for any City of Frisco leak credit request.
- Keep every receipt. Save invoices for emergency drying, repairs and temporary housing or meals if your kitchen is unusable.
How the Texas Claim Process Works
Under the Texas Prompt Payment of Claims law (Insurance Code Chapter 542), insurers generally must acknowledge your claim and begin investigating within 15 days. They must then accept or reject it within 15 business days after receiving everything they requested, and pay within five business days after approving. Exact deadlines can vary, so confirm your own situation with your insurer.
If you disagree with a decision, ask for the reasons in writing and send any missing evidence. You can also contact the Texas Department of Insurance; its toll-free number is 800-578-4677, and its water damage page links to help and complaint options.
Why Sink Leak Claims Get Denied, and How to Avoid It
- The damage looks long-term. Report the leak the day you find it and keep the failed part.
- Late reporting. Call your insurer promptly, even if you are still gathering estimates.
- No mitigation. Start drying immediately. Do not wait for the adjuster.
- Missing documentation. Take photos, keep invoices and ask the plumber to write down the cause.
- Repairs before inspection. Do not demolish or discard damaged materials until you have photographed them and the insurer has had a chance to see them.
- Confusing leaks with floods. Describe exactly where the water came from.
Not sure who to hire for the cleanup? Our guide to how to choose a water restoration company in Frisco lists what to ask before you sign anything.
Frisco Homeowners: Water Bill Relief and City Contacts
A hidden leak often shows up first on the water bill. Insurance rarely covers the extra water charge, but the City of Frisco offers a courtesy credit. Under the City of Frisco Partial Leak Credit program, the repair must be completed within 90 days of detecting the leak, the request must be filed within 90 days of the repair, and a plumber’s invoice or parts receipt must be attached. The credit is available once every 12 consecutive months, and leaks on the customer’s side of the meter remain the owner’s responsibility. Utility Billing can be reached at 972-292-5575.
For help outside business hours, the City of Frisco Water Operations page lists the Public Works number, 972-292-5800. If you are not sure where your water shuts off, see the City of Frisco FAQ on the customer water shut-off. Living in a specific community? Our Frisco neighborhoods water damage guide covers local patterns, and our Frisco service area page shows where we work.
How Water Damage Frisco Helps After a Sink Leak
Insurance decides who pays. Fast, careful drying decides how much damage there is to pay for. Our team documents the affected areas with photos and moisture readings, removes standing water, and dries cabinets, floors and walls so the damage does not spread. Learn more about our sink leak water damage service in Frisco, or see the broader water damage restoration in Frisco we provide when a leak reaches beyond the kitchen. Need to talk first? Use our contact page.
How to Prevent the Next Sink Leak
- Look under every sink each month. Feel the supply lines and trap for moisture.
- Replace aging supply lines. Follow the manufacturer’s guidance and replace any line that is kinked, corroded or bulging.
- Fix drips early. A small weep today is the long-term leak insurers exclude tomorrow. See our guide to a bathroom sink leaking underneath and water damage under a sink cabinet.
- Install leak sensors and an automatic shut-off. Compare options in our guide to smart leak detectors and shut-off valves. Some insurers offer discounts for them, so ask your agent.
Frequently Asked Questions About Sink Leaks and Homeowners Insurance
Does homeowners insurance cover a leaking sink?
Usually, yes, when the leak is sudden and accidental. A standard Texas policy generally pays for the resulting damage to cabinets, flooring, drywall and belongings, minus your deductible. It generally does not pay to repair the faucet, supply line or drain that failed, and it typically excludes damage from a leak that went on for weeks or months.
Does insurance pay to fix the pipe or faucet that leaked?
Typically no. The failed part is treated as a maintenance and wear item. Many policies do cover the cost of tearing out and replacing parts of the building, such as a cabinet back or a section of drywall, to reach the plumbing when the leak itself is a covered event.
Is a slow sink leak covered in Texas?
Usually not. Policies commonly exclude continuous or repeated seepage or leakage over time, and some set a specific window such as 14 days. If the leak was hidden and you can show it was recent, a claim may still be reviewed, so report it and let the adjuster decide rather than assuming it is excluded.
Does homeowners insurance cover mold from a sink leak?
It depends on the leak. The Texas Department of Insurance says mold that develops after a covered sudden water loss is covered, while mold from slow leaks or seepage usually is not. Some policies also cap mold payouts, so check your declarations page for a mold limit. See our guide to mold under the kitchen sink.
Will a sink leak claim raise my premium?
It can. Claims may appear in loss-history reports that insurers review at renewal or when you shop for coverage. For smaller losses, compare the repair estimate with your deductible before filing, and ask your agent how a claim could affect your renewal.
How soon should I report a sink leak to my insurer?
As soon as the water is stopped and you have photos. Policies require prompt notice, and the Texas Department of Insurance warns that a claim can be denied if you fail to protect your property from further damage. Do not wait for the adjuster before you start drying.
Does homeowners insurance cover a bathroom sink overflow?
An accidental overflow is often treated like other sudden water events and may be covered, but a loss caused by neglect, such as leaving a tap running, can be disputed. Read the cause carefully when you describe the event to your insurer.
Does insurance cover a higher water bill caused by a leak?
Not usually. The extra water charge is generally not part of the property damage claim. Frisco residents may qualify for the City of Frisco Partial Leak Credit, which requires the repair to be finished within 90 days of detection and a repair invoice with the request.
Get sink leak water damage help in Frisco
Water under the sink does not stay under the sink. Call now and we will help you stop the spread and document the damage.
This article is general information for homeowners in Frisco and North Texas. It is not legal or insurance advice. Policy wording, endorsements and deductibles vary, so confirm coverage with your insurer, your agent or the Texas Department of Insurance.