Filing a water damage insurance claim Allen TX comes down to three things: acting fast, documenting everything before cleanup starts, and having a professional restoration record backing up what you tell your adjuster. Most competitor pages for this topic say “we help with insurance” in a single sentence and stop there. This guide covers the actual step-by-step process, realistic adjuster timelines in Collin County, and what to do if your claim gets denied or underpaid.
📞 Call Us Before You Call Your Adjuster: (945) 297-3238Filing a Water Damage Insurance Claim Allen TX: Step by Step
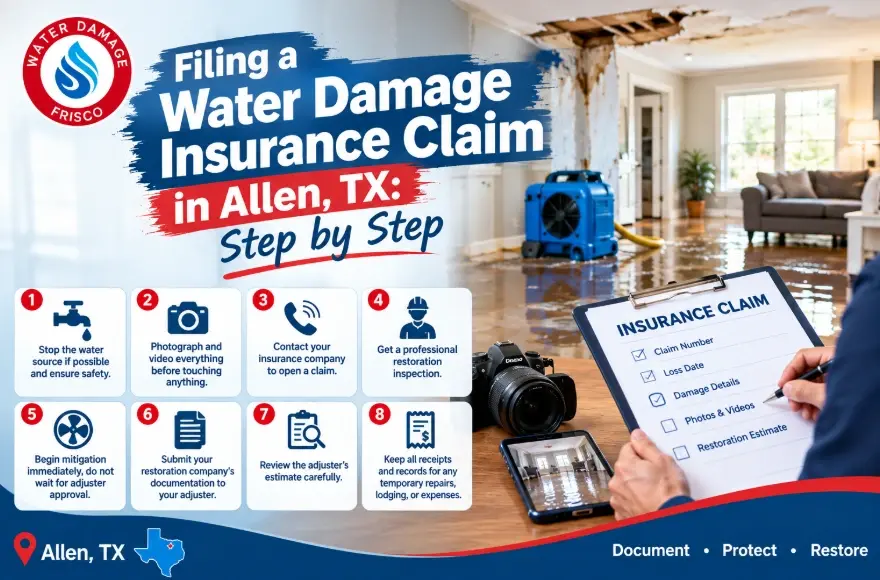
- Stop the water source if possible and ensure safety. Shut off the main valve or fixture if it is safe to do so.
- Photograph and video everything before touching anything. Wide shots of each room plus close-ups of specific damage, timestamped where possible.
- Contact your insurance company to open a claim. Do this as soon as possible; most policies require prompt notice, and delays can complicate a claim.
- Get a professional restoration inspection. A certified technician documents moisture readings, water category, and full scope with equipment your phone camera cannot replicate.
- Begin mitigation immediately, do not wait for adjuster approval to stop the damage from spreading. Most policies require you to take reasonable steps to prevent further loss, and delaying mitigation can itself become a coverage issue.
- Submit your restoration company’s documentation to your adjuster. Photos, moisture logs, and a written scope of work.
- Review the adjuster’s estimate carefully. Compare it against your restoration company’s scope before agreeing to anything.
- Keep all receipts and records for any temporary repairs, lodging, or expenses related to the loss.
What to Document Before Cleanup Begins
Insurance adjusters and restoration companies rely on documentation captured before anything is moved or cleaned. Once damaged materials are removed, that evidence is gone. Before any cleanup starts:
- Photograph every affected room from multiple angles
- Photograph the water source itself if identifiable, such as the failed appliance or pipe
- Video-walk through the property narrating what you see
- Note the date and approximate time damage was discovered
- Keep damaged items rather than discarding them until your adjuster has reviewed them or you have documented them thoroughly
Our technicians add professional-grade documentation on top of this, including moisture readings and thermal imaging that show damage your camera cannot capture, particularly inside walls and under flooring. See our water mitigation process guide for what that documentation actually involves.
Adjuster Timelines in Allen and Collin County
How fast an adjuster reaches your property depends heavily on whether your loss is isolated or part of a wider event. For a single-home incident, such as one burst pipe or a failed water heater, adjusters typically inspect within 2 to 4 days. After a major storm affecting many homes across Collin County at once, that timeline commonly stretches to 3 to 7 days simply due to adjuster demand across the region. This is one more reason to start professional mitigation immediately rather than waiting for the adjuster to arrive; most policies require you to prevent further damage regardless of when the inspection happens, and a documented head start protects your claim rather than working against it.
Local tip: If your loss followed a storm, our storm damage repair guide and the City of Allen’s Severe Weather Center both cover storm-specific documentation and safety steps that support a stronger claim.
Does Homeowner’s Insurance Actually Cover Your Water Damage?
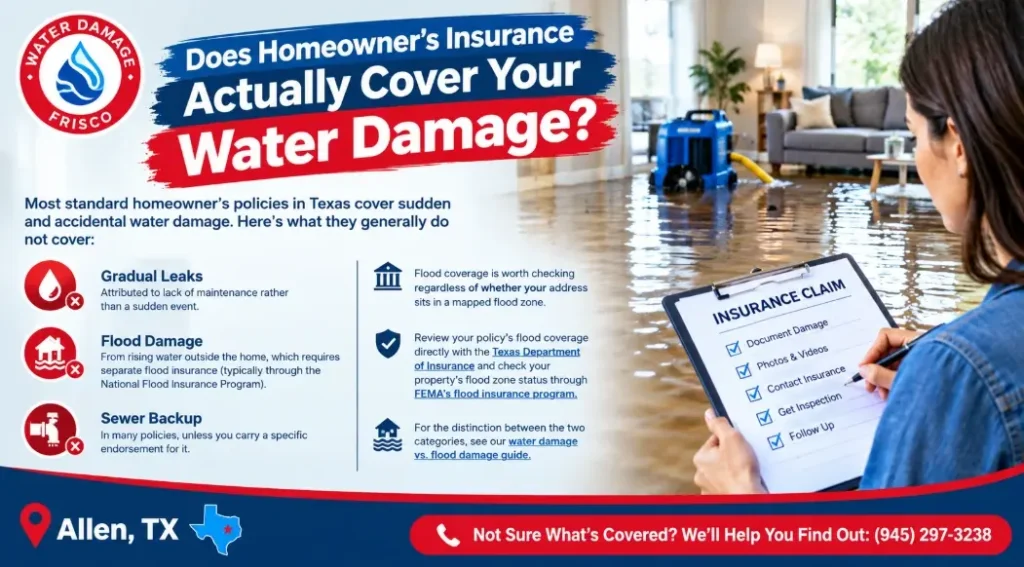
Most standard homeowner’s policies in Texas cover sudden and accidental water damage, a burst pipe, a failed supply line, or an appliance malfunction. What they generally do not cover:
- Gradual leaks attributed to lack of maintenance rather than a sudden event
- Flood damage from rising water outside the home, which requires separate flood insurance, typically through the National Flood Insurance Program
- Sewer backup in many policies, unless you carry a specific endorsement for it
Flood coverage is worth checking regardless of whether your address sits in a mapped flood zone; a significant share of flood claims nationally come from outside mapped high-risk zones. Review your policy’s flood coverage directly with the Texas Department of Insurance and check your property’s flood zone status through FEMA’s flood insurance program. For the distinction between the two categories, see our water damage vs. flood damage guide.
🔍 Not Sure What’s Covered? We’ll Help You Find Out: (945) 297-3238What If Your Claim Is Denied or Underpaid?
A denial or a lowball estimate is not necessarily the final word. If you disagree with your insurer’s decision:
- Ask for the specific reason in writing. Insurers must provide a basis for denial; a vague verbal explanation is not enough to act on.
- Request a reinspection if you believe damage was underestimated or missed.
- Provide additional documentation that supports a higher or different estimate, including your restoration company’s independent scope of work.
- Contact the Texas Department of Insurance Help Line at 800-252-3439 for guidance specific to your situation.
- File a formal complaint with TDI if you believe the company violated your policy terms or state law. TDI helps Texans recover additional claim payments and refunds every year through this process; you can start at the TDI insurance complaint portal.
- Consult a Texas attorney if the dispute remains unresolved after filing a complaint, particularly for large or complex claims.
This is general information, not legal advice. For guidance specific to your policy and claim, consult a licensed Texas insurance professional or attorney.
Why Documentation From a Restoration Company Strengthens Your Claim
Adjusters see thousands of claims, and a claim backed by third-party, professionally documented evidence, moisture readings, thermal imaging, and a detailed written scope, moves faster and holds up better than photos and a verbal description alone. We provide this documentation as a standard part of every Allen job, not an upsell, and submit it directly to your adjuster. See our Allen water damage restoration guide for what that inspection and documentation process looks like from the first call.
Fire and Storm-Related Claims
If your loss involved fire in addition to water, whether from firefighting efforts or a separate event, the claims process runs largely in parallel but the documentation differs. See our fire damage restoration guide for that side of the process. If you are weighing whether to repair before selling a damaged property, our guide to selling a fire or storm-damaged home in Allen explains how a completed, documented claim affects that decision.
📋 Let Us Document and File Your Claim With You: Call (945) 297-3238Related Resources for Allen, TX Homeowners
Allen, TX: Full Restoration Service Overview · Water Damage Restoration Allen, TX · Fire Damage Restoration Allen, TX · Storm Damage Repair Allen, TX · Water Damage Restoration Cost Allen, TX · Fire Damage Restoration Cost Allen, TX · Best Restoration Companies in Allen, TX · Water Damage Insurance Claims in Texas (Statewide Guide) · Why IICRC Certification Matters
Serving Allen and Nearby Communities
We handle insurance documentation and claims coordination for homeowners throughout Allen, including neighborhoods like Twin Creeks, Watters Creek, Bethany Lakes, and Historic Downtown Allen, and across the rest of North Texas. See our Celina insurance claim guide for comparison. If you need service outside Allen, see our location pages for McKinney, Plano, Frisco, Carrollton, Celina, Prosper, The Colony, Little Elm, Oak Point, and Dallas. You can also see our complete list of restoration services and our what to look for in a restoration company guide.
Frequently Asked Questions
Contact your insurance company to open a claim as soon as possible, document all damage with photos and video before cleanup begins, get a professional restoration inspection, and submit the resulting documentation to your adjuster. We handle the documentation and adjuster coordination directly as part of every job.
For an isolated incident like a single burst pipe, adjuster inspections typically happen within 2 to 4 days. After a major storm affecting many homes across Collin County at once, that timeline commonly extends to 3 to 7 days due to adjuster demand.
Most standard homeowner’s policies cover sudden and accidental water damage, such as a burst pipe or failed appliance hose. Gradual leaks from lack of maintenance and flood damage from rising water are typically excluded and require separate coverage.
First, ask your insurer in writing for the specific reason for denial or the underpayment. If you disagree, you can request a reinspection, provide additional documentation, or file a complaint with the Texas Department of Insurance, which helps Texans recover additional claim payments and refunds every year.
Standard homeowner’s insurance does not cover flood damage from rising water. Flood coverage requires a separate policy, typically through the National Flood Insurance Program, and is worth checking regardless of whether your property sits in a mapped flood zone.
A water damage insurance claim moves faster and settles more fairly when it is backed by real documentation from the start. Whether you are filing a claim right now or just want to understand the process before disaster strikes, our IICRC-certified team can help you document, file, and follow through, at no cost for the initial inspection.
🚨 Start Your Claim With a Free Inspection: (945) 297-3238