Does Homeowners Insurance Cover Flood Damage Carrollton TX?
If you’re asking does homeowners insurance cover flood damage in Carrollton, TX, the answer catches most homeowners off guard: it doesn’t, and it never has. Your policy’s “water damage” section only applies to sudden, accidental water from inside your home — a burst pipe, an overflowing water heater, a failed supply line. The moment water comes from outside — rising creek water, storm runoff, or an overwhelmed drainage system — it’s legally classified as a flood, and flood is a named exclusion on every standard homeowners policy sold in Texas.
That distinction matters more in Carrollton than in a lot of North Texas suburbs, because Carrollton sits along several active flood sources — the Elm Fork Trinity River, Furneaux Creek, and Hutton Branch all run through the city, and heavy rain events regularly push water past their banks into nearby streets and yards.
Why Doesn’t Standard Homeowners Insurance Cover Flooding?
Every HO-3 and HO-5 policy contains a water damage exclusion clause that specifically carves out flooding, storm surge, and overflow from rivers, creeks, or lakes. Insurers treat flood risk as a separate, geographically concentrated hazard — one bad storm can generate thousands of simultaneous claims in a single flood-prone area, which is financially different from the random, house-by-house risk of a burst pipe. That’s why flood coverage was split off into its own federally backed program (the NFIP) back in 1968, instead of being bundled into standard homeowners policies.
This is also the single biggest coverage gap homeowners discover only after they’ve already filed a claim. If your Carrollton home has taken on water and you’re not sure which category your damage falls into, our step-by-step Carrollton water damage insurance claim guide walks through how adjusters draw that line — and what documentation gets a legitimate water-damage claim approved instead of denied.
What Does NFIP Flood Insurance Actually Cover?
An NFIP policy is the standard way Carrollton homeowners fill the flood gap left by their regular insurance. Here’s what it does and doesn’t include:
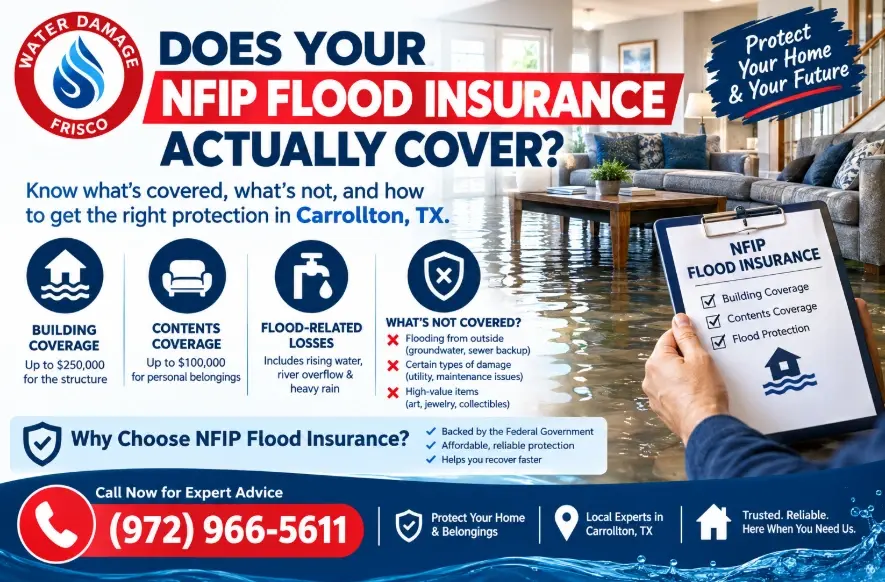
- Building coverage: up to $250,000 for the structure itself — foundation, electrical, HVAC, built-in appliances, flooring.
- Contents coverage: up to $100,000 for personal belongings, purchased separately from building coverage.
- Waiting period: most new NFIP policies take 30 days to go into effect, so it isn’t something you can buy the day a storm is forecast.
- Average cost: roughly $800 per year nationally, though homes in a FEMA-designated Special Flood Hazard Area can run $1,500+ annually depending on elevation and flood zone.
- What it excludes: temporary living expenses, landscaping, pools, fences, and detached structures beyond basic limits — none of which a standard NFIP policy reimburses.
| Coverage Type | Covers Flood Damage? | Typical Limits |
|---|---|---|
| Standard Homeowners (HO-3/HO-5) | No | N/A — explicitly excluded |
| NFIP Flood Insurance | Yes | $250,000 building / $100,000 contents |
| Private Flood Insurance | Yes | Often higher, carrier-dependent |
For the official coverage breakdown and current rate factors, the National Flood Insurance Program (FloodSmart.gov) and the Texas Department of Insurance’s flood insurance guide are both worth reading directly before you buy a policy.
Private Flood Insurance: A Growing Alternative for Carrollton Homeowners
Private flood insurance has become a real option alongside the NFIP in the last several years. Depending on the carrier, private policies can offer higher building and contents limits than the NFIP’s $250,000/$100,000 caps, sometimes shorter waiting periods, and coverage for extras like temporary living expenses that NFIP policies don’t include. The tradeoff is that pricing and availability vary block by block, so it’s worth getting quotes from both an NFIP-participating agent and a private flood carrier before deciding — particularly for larger or higher-value Carrollton homes where the NFIP’s caps wouldn’t fully rebuild the structure.
Is Your Carrollton Home Actually at Flood Risk?
- The city sits along the Elm Fork Trinity River, Furneaux Creek, and Hutton Branch — all active flood sources during heavy North Texas rain events.
- Carrollton has operated under its own Stormwater and Flood Protection Ordinance since 1987, administered by the City Engineer as the city’s floodplain administrator, specifically because of recurring erosion and flooding problems.
- The Texas Department of Insurance places Carrollton inside “Flash Flood Alley,” the band of Central and North Texas the state flags as consistently high flood risk.
- Nationally, roughly 40% of NFIP claims come from outside officially mapped high-risk flood zones — meaning a Carrollton address outside a FEMA Special Flood Hazard Area is not automatically a safe bet.
You can look up your specific address on the FEMA Flood Map Service Center to see which flood zone it falls in, and the City of Carrollton‘s engineering department can answer questions about local drainage and floodplain permitting.
What Happens If Your Carrollton Home Floods Without Flood Insurance?
Without a flood policy, you’re paying for cleanup, structural drying, and repairs entirely out of pocket. Federal disaster assistance is not a substitute — it only becomes available after a presidential disaster declaration, and in most cases it’s structured as a low-interest loan you have to repay, not a grant. If your area doesn’t receive a formal declaration, there’s no federal backstop at all. That’s the gap flood insurance is designed to close, and it’s also why acting fast once water is in your home matters just as much as the policy itself — every hour water sits against drywall, flooring, and framing increases both the damage and the cost to fix it.
Water Damage vs. Flood Damage: Why the Distinction Matters for Your Claim
Insurance adjusters draw a hard line between the two, and it decides whether your claim gets paid:
- Water damage (usually covered): a burst pipe, a failed washing machine hose, an overflowing tub — sudden, accidental, and internal to the home.
- Flood damage (never covered by a standard policy): rising creek or river water, storm surge, or surface water runoff that enters from outside — regardless of how little water actually comes in.
If you’re not sure which category your damage falls into, our Carrollton water damage insurance claims guide covers documentation and adjuster expectations in detail, and the statewide Texas water damage insurance claim overview explains how this distinction plays out under Texas insurance law specifically.
How to Get Flood Insurance in Carrollton, TX
- Check your property’s flood zone on the FEMA Flood Map Service Center.
- Contact your existing homeowners insurance agent — most write NFIP policies alongside standard coverage — or get a quote from a private flood carrier.
- Budget for the 30-day NFIP waiting period; don’t wait until a storm is already forecast.
- If your lender requires flood insurance because you’re in a mapped high-risk zone, confirm your policy meets their minimum coverage requirement.
- Re-shop annually — private flood insurance pricing has been shifting quickly, and rates can differ significantly between carriers for the same address.
What to Do If Your Carrollton Home Just Flooded
If water is actively in your home right now, insurance questions can wait until people and pets are safe. Once it’s safe to act:
- Photograph and video every affected room and item before moving or discarding anything.
- Shut off electricity to flooded areas if it’s safe to reach the breaker.
- Call your insurance company (or the NFIP directly if you’re already covered) to open a claim.
- Start extraction and drying as soon as possible — standing water and saturated materials begin growing mold within 24–48 hours.
Our Carrollton flood damage restoration guide covers exactly who to call and what happens during the cleanup process, and our 24/7 emergency water extraction & mitigation team can be on-site quickly once you’ve documented the damage.
Frequently Asked Questions About Flood Damage Insurance in Carrollton, TX
Does homeowners insurance cover flood damage in Carrollton, TX?
No. Standard HO-3 and HO-5 policies exclude flood damage entirely. You need a separate NFIP or private flood insurance policy for coverage.
What is the NFIP and how much does it cover?
The National Flood Insurance Program is a federally backed flood insurance program administered by FEMA, covering up to $250,000 for a home’s structure and up to $100,000 for personal belongings.
How much does flood insurance cost in Carrollton, TX?
Average NFIP premiums run around $800 per year nationally, though homes in a mapped high-risk flood zone can pay $1,500 or more annually. Private flood insurance pricing varies by carrier and address.
Is Carrollton, TX in a FEMA flood zone?
Parts of Carrollton near the Elm Fork Trinity River, Furneaux Creek, and Hutton Branch fall within FEMA-mapped flood zones. Check your specific address on the FEMA Flood Map Service Center, since flood risk varies block by block.
How long is the NFIP waiting period before coverage starts?
Most new NFIP policies take 30 days to take effect, so flood insurance needs to be purchased well before a storm is forecast, not during one.
What’s the difference between water damage and flood damage for an insurance claim?
Water damage from an internal, sudden source (like a burst pipe) is typically covered by standard homeowners insurance. Flood damage from external sources like rising creek water or storm runoff is not, and requires a separate flood policy.
Our team responds 24/7 for emergency water extraction, structural drying, and full flood damage restoration in Carrollton and the surrounding DFW area.
Get a Free Damage AssessmentCall (945) 297-3238 | info@waterdamagefrisco.org